
Release: 2026-9.57.0
Update: October 20, 2026
Canada (26R2 Only)
Federal and Multiple Provinces
Income Tax – effective varies, see below.
The tax engine now rounds the Basic Personal Amount (BPA) to two decimal places before using it to figure the tax credit. This follows the rule in CRA T4127. If the third digit after the decimal is 5 or more, the second digit goes up by one. If it is less than 5, the extra digits are dropped.
This changes the federal amount and the Manitoba, Nova Scotia, and Yukon amounts. Employees whose income is outside the phase-out range get a flat amount, so nothing changes for them.
The change applies to pay dates starting January 1, 2023 for the federal, Nova Scotia, and Yukon amounts, and January 1, 2025 for Manitoba. Results for earlier tax years may move by a cent or so. We also made the 2026 federal phase-out multiplier more precise (0.021066431297215). Without this, the rounded 2026 amount could be one cent higher than the CRA figure.
Nova Scotia
Workers Compensation – effective January 1, 2027
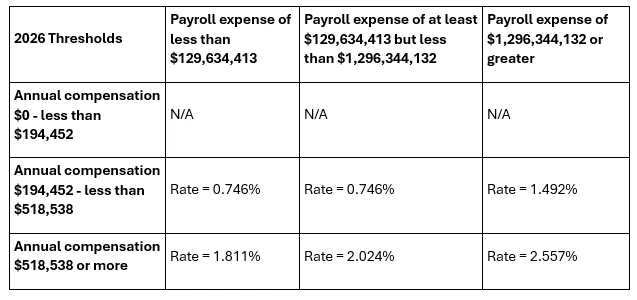
The average assessment rate decreased from 2.65% to 2.25% ($2.25 per $100 of assessable earnings), and the maximum assessable earnings increased from $79,900 to $83,300, for a maximum assessment of $1,874.25 ($83,300 x 2.25%).
United States
Federal
Dependent Custodial Account – effective July 4, 2026
The $2,500 yearly limit for the Dependent Custodial Account (Trump Account) benefit now counts the employee’s contribution and the employer’s contribution together. Before, it counted only the employer’s. This follows the IRS’s proposed rules (RIN 1545-BS19).
The employee’s contribution counts toward the limit first, across all of the employee’s plans. The employer’s contribution is limited to what is left. A limit override on a plan now applies only to that plan’s employer contribution, like other benefit types.
This applies to pay dates on or after July 4, 2026. The limit amount and start date have not changed. If an employee’s combined contributions are $2,500 or less, nothing changes. If they are over $2,500, amounts will change, usually going lower. These amounts affect subject wages for the federal taxes, California, South Carolina, and the state unemployment wage bases that follow the HSA rules.
Arizona
Income Tax – effective July 4, 2026
The taxability treatment for the Dependent Custodial Account (Trump Account) benefit has been updated to conform to the federal treatment, per Arizona House Bill 4168. Employee contributions are now pre-tax, reducing subject wages by the contribution amount. Employer contributions are unchanged and continue not to increase subject wages. This brings Arizona in line with the other confirmed conforming states: Alabama, Georgia, Indiana, Minnesota, and West Virginia. Behavior for pay dates before July 4, 2026 is unchanged.
Colorado
Workers' Compensation – effective October 20, 2026
We added a helpful description for ‘Is Corporate Officer’ on the Tax Maintenance (PR208002) ~ Tax Codes or Employee Payroll Settings (PR208000) ~ Tax Settings. Select if the employee is a corporate officer.
Paid Family and Medical Leave – effective January 1, 2026
When we split an employer pick-up contribution across an employee’s work locations in a state, a location now counts if the employee earned any of these wage types there: Regular, Supplemental, Overtime, Tips, RUIA compensation, minister housing allowance, or custom wages. Before, only Regular wages counted.
When an employee works at more than one location in a state, we split their employer pick-up contribution across those locations. We fixed a mistake in how that split was figured. Before, some locations got too small a share and the last location got the leftover. Now every location gets a fair share based on all the wages paid there.
Example: A $9.00 pick-up is split between Denver and Boulder. Each location now gets $4.50.
Delaware
Paid Family and Medical Leave – effective January 1, 2026
When we split an employer pick-up contribution across an employee’s work locations in a state, a location now counts if the employee earned any of these wage types there: Regular, Supplemental, Overtime, Tips, RUIA compensation, minister housing allowance, or custom wages. Before, only Regular wages counted.
When an employee works at more than one location in a state, we split their employer pick-up contribution across those locations. We fixed a mistake in how that split was figured. Before, some locations got too small a share and the last location got the leftover. Now every location gets a fair share based on all the wages paid there.
Example: a $5.27 Delaware pick-up is split between Wilmington and Dover. Wilmington now gets $2.64 and Dover gets $2.63.
Illinois
State Unemployment Tax – effective October 20, 2026
The tax engine now supports the Illinois small-employer rate reduction for state unemployment tax (SUTA). To use it, send the employer’s total wages for the quarter, across all employees, in the new QUARTERLY_TOTAL_WAGES parameter on the Tax Maintenance (PR208002) ~ Tax Codes. If that amount is under $50,000, the tax engine caps the employer’s Illinois SUTA rate at 5.4%. If the employer’s rate is already 5.4% or lower, nothing changes.
Before, you had to set the $50,000 limit and the 5.4% rate yourself and fix Illinois SUTA after the quarter ended. Now the tax engine does it for you.
This is optional. If you don’t send the parameter, nothing changes. At $50,000 or more, the regular rate is used. You can find the parameter in the list of jurisdiction miscellaneous parameters.
Kentucky
Salem OLF – effective October 1, 2026
Tax has been added with a 1.0% tax rate and no wage base limit. This tax applies to all persons working within the City of Salem, Livingston County, Kentucky, per Ordinance 2026-05. It stacks with the existing Livingston County OLF rather than replacing it, and follows the standard Kentucky OLF definition of taxable compensation, which includes pre-tax salary-reduction contributions to retirement, deferred-compensation, and cafeteria/fringe benefit plans. The tax does not apply to compensation received by Kentucky National Guard members for active duty or unit training, precinct election workers, domestic servants employed directly in a private home, or persons conducting yard, garage, or patio sales lasting three or fewer days and not repeated within thirty days. Independent contractors are classified as employees under the ordinance, but employers do not withhold on them. Employers submit a list of 1099 contractors to the City, and each contractor files and pays individually via the quarterly 1099 return. The City of Salem administers the tax, and returns are remitted to the City. Withholding is filed monthly by default; employers whose monthly liability is under $100 may file quarterly instead, reverting to monthly if quarterly liability exceeds $300.
Whitesville OLF – effective October 1, 2026
Added with a 1.15% tax rate and no wage base limit. This tax applies to all wages and compensation for work performed within the City of Whitesville, Daviess County, Kentucky, per Ordinance No. 25.07. It does not stack with the existing Daviess County - OLF. When both are set up for a Whitesville work location, only Whitesville - OLF is calculated, and Daviess County - OLF returns $0. Work elsewhere in Daviess County remains subject to Daviess County - OLF only. Withholding is remitted to the City of Whitesville quarterly, and the first return, for October 1 through December 31, 2026, is due by January 31, 2027.
Maine
Income Tax – effective January 1, 2026
The standard deduction used for withholding purposes (Percentage Method, Step 3) has increased from $12,450 to $12,850 for single filers and from $27,750 to $28,550 for married filers. The phase-out thresholds are unchanged at $102,250 for single filers and $204,550 for married filers. The Maine State Tax also began calculating a new 2% surcharge on the portion of annualized taxable income over $1,000,000 for single filers and $1,500,000 for married filers. The rate schedule (5.80%, 6.75%, and 7.15%) and its bracket thresholds are unchanged. The personal exemption remains $5,300, and the nonresident alien rate remains 5%. The flat rate on separately paid supplemental wages remains 5% and does not pick up the surcharge; supplemental wages paid together with regular wages do. Per Maine Revenue Services, implementing the revised withholding tables, including the surcharge, is optional for 2026 and becomes mandatory January 1, 2027. Symmetry applies the surcharge by default for 2026 pay dates.
Paid Family and Medical Leave – effective January 1, 2026
When we split an employer pick-up contribution across an employee’s work locations in a state, a location now counts if the employee earned any of these wage types there: Regular, Supplemental, Overtime, Tips, RUIA compensation, minister housing allowance, or custom wages. Before, only Regular wages counted.
When an employee works at more than one location in a state, we split their employer pick-up contribution across those locations. We fixed a mistake in how that split was figured. Before, some locations got too small a share and the last location got the leftover. Now every location gets a fair share based on all the wages paid there.
Example: A $7.00 pick-up is split between Portland and Bangor. Each location now gets $3.50.
Massachusetts
Paid Family and Medical Leave – effective January 1, 2026
When we split an employer pick-up contribution across an employee’s work locations in a state, a location now counts if the employee earned any of these wage types there: Regular, Supplemental, Overtime, Tips, RUIA compensation, minister housing allowance, or custom wages. Before, only Regular wages counted.
When an employee works at more than one location in a state, we split their employer pick-up contribution across those locations. We fixed a mistake in how that split was figured. Before, some locations got too small a share and the last location got the leftover. Now every location gets a fair share based on all the wages paid there.
Example: An $8.10 pick-up is split between Boston and Springfield. Each location now gets $4.05.
Michigan
State Unemployment Tax – effective October 20, 2026
We added two new settings for Michigan employees on the Tax Maintenance (PR208002) ~ Tax Codes or Employee Payroll Settings (PR208000) ~ Tax Settings.
- Location Code: Enter the code for the location where the employee works. You can set a default and change it for any one employee.
- Is Corporate Officer: Select this if the employee is a corporate officer. This is set for each employee.
These settings feed the Aatrix file for Michigan’s quarterly unemployment report, Form UIA 1028. If you leave them blank for an employee, that employee gets no entry for them in the file.
Minnesota
Paid Family and Medical Leave – effective October 20, 2026
We fixed a problem with the Minnesota Paid Leave (FLI) Employee Contribution Percentage setting. When you set it to 0, the tax was still split 50/50 between the employer and the employee. Now a setting of 0 means the employer pays the full amount and the employee pays nothing.
Paid Family and Medical Leave – effective January 1, 2026
When we split an employer pick-up contribution across an employee’s work locations in a state, a location now counts if the employee earned any of these wage types there: Regular, Supplemental, Overtime, Tips, RUIA compensation, minister housing allowance, or custom wages. Before, only Regular wages counted.
When an employee works at more than one location in a state, we split their employer pick-up contribution across those locations. We fixed a mistake in how that split was figured. Before, some locations got too small a share and the last location got the leftover. Now every location gets a fair share based on all the wages paid there.
Example: a $5.27 Delaware pick-up is split between Wilmington and Dover. Wilmington now gets $2.64 and Dover gets $2.63.
Nebraska
Income Tax – effective January 1, 2027
The withholding brackets for single and married filers have been updated, and the value of an annual withholding allowance has increased from $2,440 to $2,510. The supplemental tax rate remains 3.5%
New Jersey
Employer State Disability Insurance (SDI) - effective January 1, 2027
The wage base has increased from $44,800 to $46,400. The employer rate remains 0.5% through June 30, 2027.
Family Leave Insurance - effective January 1, 2027
The wage base has increased from $171,100 to $177,100. The employee rate remains 0.23%.
State Disability Insurance (Employee SDI) - effective January 1, 2027
The wage base has increased from $171,100 to $177,100. The employee rate remains 0.19%.
State Unemployment Tax - effective January 1, 2027
The wage base has increased from $44,800 to $46,400. The new-employer rate remains 2.6825% through June 30, 2027
State Unemployment Tax (Employee SUI) - effective January 1, 2027
The wage base has increased from $44,800 to $46,400. The tax rate remains 0.425% (0.3825% U.I. + 0.0425% W.F./S.W.F.).
Workforce Development/Supplemental Workforce Funds - effective January 1, 2027
The wage base has increased from $44,800 to $46,400. The rate remains 0.1175% through June 30, 2027.
North Carolina
Workers' Compensation – effective October 20, 2026
We added a helpful description for ‘Is Corporate Officer’ and ‘Site/Location Code’ on the Tax Maintenance (PR208002) ~ Tax Codes or Employee Payroll Settings (PR208000) ~ Tax Settings.
- Is Corporate Officer: Select if the employee is a corporate officer.
- Site/Location Code: The code of the location where the employee works or the unit to which the employee is assigned.
Ohio
Delta City Tax – effective January 1, 2027
The tax will be administered by RITA. The tax rate remains 1.5%, the credit for taxes paid to other municipalities remains 100%, and the credit limit remains 1%.
Oregon
Income Tax = effective January 1, 2020
When an employee has not turned in a Form OR-W-4, the tax engine now withholds a flat 8% of their Oregon wages. This is the rate set by Oregon HB 2119.
If you send either FILINGSTATUS or TOTALALLOWANCES, the tax engine treats the form as on file and uses the usual formula. If you send S and 0 for employees without a form, nothing changes for them. To use the flat rate, stop sending those values.
What to expect: low earners will now have tax withheld. For example, a $100 paycheck that used to withhold $0 now withholds $8. For people who earn more than $130,000 a year, the flat rate withholds less than the old formula.
Paid Family and Medical Leave – effective January 1, 2027
When we split an employer pick-up contribution across an employee’s work locations in a state, a location now counts if the employee earned any of these wage types there: Regular, Supplemental, Overtime, Tips, RUIA compensation, minister housing allowance, or custom wages. Before, only Regular wages counted.
When an employee works at more than one location in a state, we split their employer pick-up contribution across those locations. We fixed a mistake in how that split was figured. Before, some locations got too small a share and the last location got the leftover. Now every location gets a fair share based on all the wages paid there.
Example: A $6.40 pick-up is split between Portland and Eugene. Each location now gets $3.20.
Pennsylvania
State Unemployment Tax – ACTION REQUIRED - effective October 20, 2026
Employee SUI now counts the employer’s educational assistance contributions as wages. This applies to both educational assistance benefit types added in release 2026.7.2. Pennsylvania does not follow Section 127, so the whole contribution is taxable. There is no $5,250 exclusion.
Pennsylvania SIT and employer SUTA already did this correctly. Only employee SUI was missing it.
Action Required: Starting with this release, employee SUI includes these contributions. Checks calculated earlier did not, review affected Pennsylvania employees’ year-to-date wages and employee SUI and make corrections if needed.
Washington
Paid Family and Medical Leave – effective January 1, 2026
When we split an employer pick-up contribution across an employee’s work locations in a state, a location now counts if the employee earned any of these wage types there: Regular, Supplemental, Overtime, Tips, RUIA compensation, minister housing allowance, or custom wages. Before, only Regular wages counted.
When an employee works at more than one location in a state, we split their employer pick-up contribution across those locations. We fixed a mistake in how that split was figured. Before, some locations got too small a share and the last location got the leftover. Now every location gets a fair share based on all the wages paid there.
Example: A $7.50 pick-up is split between Seattle and Spokane. Each location now gets $3.75.
Washington DC
Workers' Compensation – effective October 20, 2026
We added a helpful description for ‘Unit/Location Code’ on the Tax Maintenance (PR208002) ~ Tax Codes or Employee Payroll Settings (PR208000) ~ Tax Settings. The code of the employer’s unit or location.
Wyoming
Workers' Compensation – effective October 20, 2026
We added a helpful description for ‘Class Code’ and ‘Coverage Type’ on the Tax Maintenance (PR208002) ~ Tax Codes or Employee Payroll Settings (PR208000) ~ Tax Settings.
- Class Code: Is Corporate Officer: The six-character Wyoming NAICS code. For a corporate officer, the six-character code is followed by the letter C, for a total of seven characters.
- Coverage Type: The type of wages.